Startup valuations make headlines. But when a company is acquired, the amount founders, investors and employees actually receive can be dramatically different from what their ownership percentages suggest.
Imagine your startup is acquired for CHF 100 million. According to the cap table, you still own 20% of the company. Simple mathematics suggests that you should walk away with CHF 20 million. Unfortunately, startup exits rarely work that way. Between the announced acquisition price and the money that eventually reaches your bank account lie liquidation preferences, different share classes, vesting schedules, exercise costs, taxes and sometimes contractual obligations that extend years beyond the acquisition itself.
This distinction is particularly important in venture-backed startups, where financing agreements often determine who gets paid first and how the remaining proceeds are distributed. A successful exit for the company does not automatically translate into an equally successful financial outcome for everyone involved.
The Cap Table Only Tells Half the Story
A cap table shows who owns what percentage of a company. What it doesn’t necessarily reveal is how the proceeds of an acquisition will be distributed. In venture capital, investors frequently receive preferred shares that come with liquidation preferences, giving them priority over ordinary shareholders when a company is sold.
Consider a startup that has raised CHF 20 million from investors. Those investors own 40% of the company, while founders and employees collectively own the remaining 60%. The startup is eventually acquired for CHF 30 million. Without special rights, investors would receive CHF 12 million and founders and employees would share CHF 18 million.
However, if the investors hold a 1x non-participating liquidation preference, they can instead choose to recover their original CHF 20 million investment before the remaining proceeds are distributed. That leaves just CHF 10 million for founders and employees. With participating preferred shares, the situation becomes even more challenging: Investors could first receive their CHF 20 million and then participate in the remaining proceeds according to their ownership percentage. In this simplified example, they would receive CHF 24 million in total, leaving only CHF 6 million for everyone else.
The company sells for exactly the same CHF 30 million in all three scenarios. Yet the financial outcomes could hardly be more different. Add multiple financing rounds, different preference seniorities or outstanding debt, and the distribution becomes even more complex.
This is why founders should pay as much attention to investor rights as they do to valuation. A higher valuation accompanied by unfavorable terms can ultimately produce a worse outcome than a more modest valuation with a clean and founder-friendly capital structure.
Employee Equity: Valuable on Paper, Complicated in Reality
The gap between theoretical ownership and actual proceeds can be even more confusing for startup employees. Stock options and other equity compensation programs are frequently used to attract talent, especially when young companies cannot compete with the salaries offered by established technology companies. Employees sometimes accept lower cash compensation in exchange for the possibility of a substantial payout when the company is acquired.
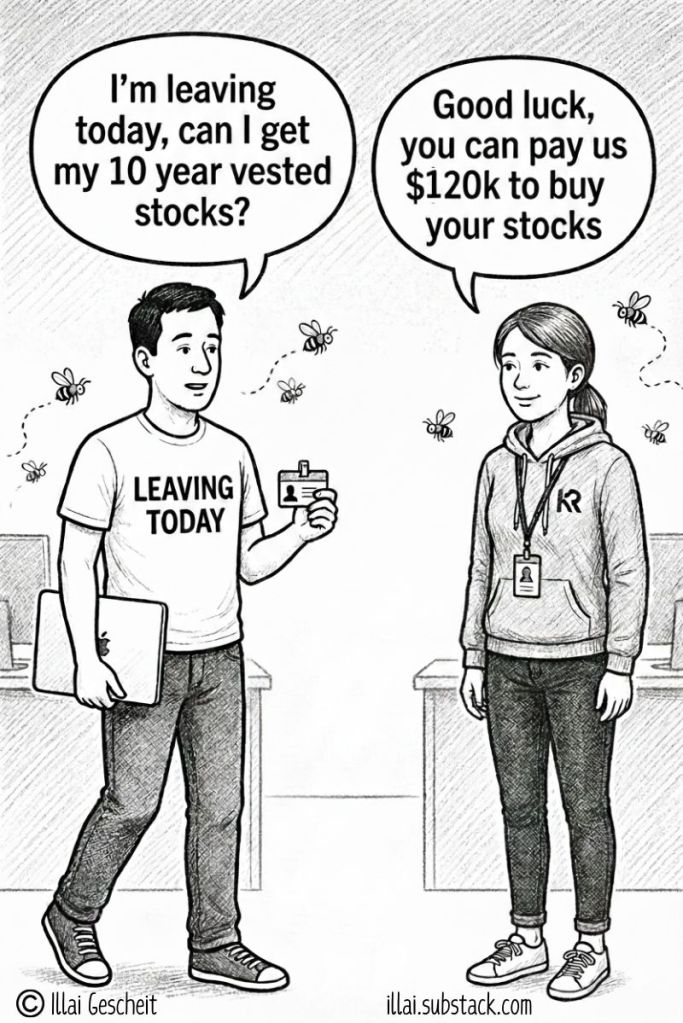
But a stock option package described as being worth CHF 200,000 is not the same as having CHF 200,000 in the bank. Employees need to understand whether they are receiving actual shares, stock options or virtual equity, as well as the conditions attached to those instruments.
Vesting is particularly important. Imagine an employee receives 10,000 stock options vesting over four years. After two years, only 5,000 may have vested. If the company is acquired at that point, the remaining options could accelerate, expire or be converted into a new compensation arrangement, depending on the equity plan and acquisition agreement. Some transactions also require employees to remain with the acquiring company for several years before receiving their full compensation.
Exercise costs and taxes create another important difference between headline values and actual payouts. Suppose an employee holds 5,000 exercisable options with an exercise price of CHF 10 per share. If the applicable exit proceeds amount to CHF 30 per share, the gross economic gain is CHF 100,000, not CHF 150,000. Depending on the jurisdiction and the structure of the employee participation plan, taxes can reduce the amount available even further. In Switzerland, the tax treatment of employee participation programs requires particular attention and should be clarified early.
An acquisition can therefore create very different outcomes for employees working at the same company. One person may receive a substantial cash payment immediately, while another might have to wait several years, continue working for the buyer or discover that much of the expected value disappears through contractual conditions.
Why Founders Should Stop Optimizing Only for Valuation
Startup founders naturally celebrate higher valuations. A large funding round attracts media attention, helps with recruiting and reduces dilution in the immediate financing round. However, it also creates expectations about the company’s future performance and eventual exit value.
Consider a startup that raises capital at a CHF 200 million valuation but is eventually sold for CHF 100 million. A hundred-million-franc exit sounds impressive, yet the outcome for founders may be disappointing if investors hold significant preferential rights. The valuation achieved during fundraising tells us very little about how the acquisition proceeds will ultimately be shared.
Founders should therefore negotiate financing terms with the eventual exit in mind. Liquidation preferences, participation rights, investor vetoes, anti-dilution provisions and the treatment of employee equity can be just as important as the headline valuation. These conditions may seem secondary when capital is readily available and growth expectations are high, but they become critical when an actual acquisition offer arrives.
One practical approach is to model several potential exit scenarios before signing a financing agreement. What happens if the company sells for CHF 30 million, CHF 100 million or CHF 300 million? How much do investors receive under each scenario? How much remains for founders and employees? And at which exit value do preference rights stop materially affecting the distribution?
Running these calculations can reveal that a financing round with a lower valuation but simpler terms may create substantially more value for common shareholders. The objective should not be to maximize theoretical wealth on paper, but to build a company whose success translates into meaningful financial outcomes for the people who helped create it.
The Real Meaning of a Successful Exit
The startup ecosystem tends to measure success through fundraising announcements, valuations and acquisition prices. These figures are easy to communicate and make compelling headlines, but they can create a misleading impression of the wealth generated by a transaction.
A company can achieve a remarkable exit while some employees receive little financial benefit. A founder can retain a significant ownership percentage yet receive far less than expected. And an employee who appears to hold a valuable equity package may discover that the actual payout depends on exercise costs, taxation, vesting conditions or continued employment after the acquisition.
For founders, the lesson is to understand the economic consequences of financing terms before accepting investment. For employees, it is to understand exactly what their equity compensation represents and when it can realistically become liquid. And for investors, transparent and balanced incentive structures can help ensure that the people building the company remain motivated throughout its development.
Ultimately, valuation is not wealth, ownership is not liquidity, and an announced exit price is not the same as money in the bank.
The next time a startup announces a spectacular acquisition, perhaps we should ask a different question. Not simply how much the company was sold for, but how much founders, investors and employees actually took home.
Because that is where the real exit story begins.


Kommentar verfassen