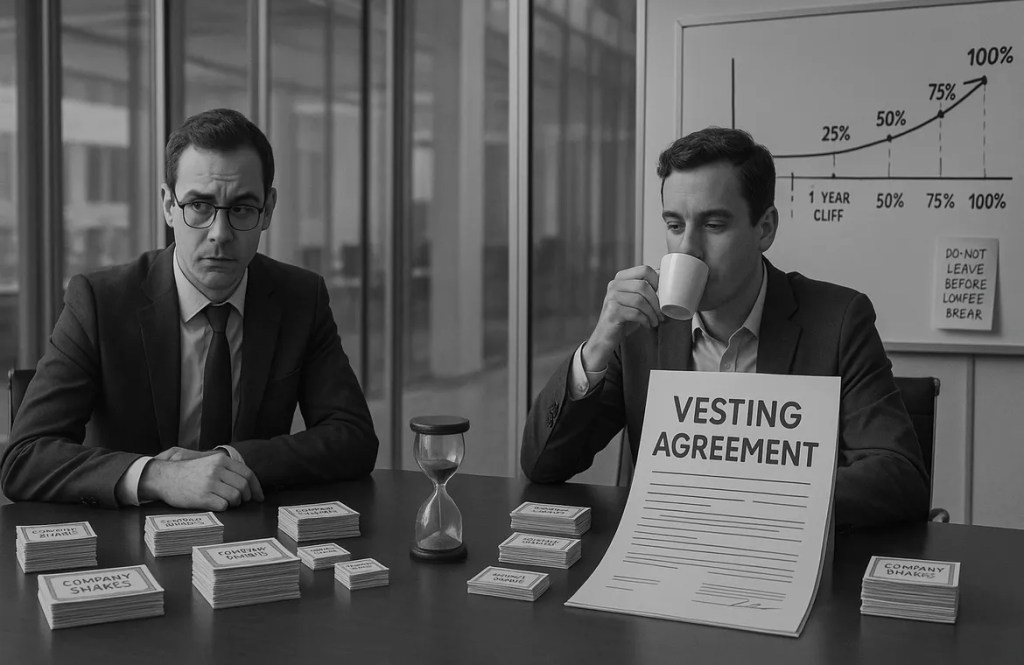
Four-year vesting with a one-year cliff has become the default for startup founders. It sounds sensible, it is widely used, and at the time of incorporation there are usually more urgent things to worry about. The problem is that founder vesting often gets designed around the wrong question: What happens if someone leaves after six months?
The much harder question is what happens if someone leaves after two and a half or three years.
By that point, a founder may already have vested a significant part of their equity. In a three-founder company, that can easily mean a double-digit percentage of the business. If that person leaves, the remaining founders may suddenly find themselves building the company for another five, seven or even ten years while a former co-founder continues to participate substantially in the upside.
That is where people quickly start talking about “dead equity.” But the term can be misleading. A founder who spent three years building the product, winning the first customers, hiring the early team and taking considerable personal risk has created real value. Their equity is not automatically undeserved simply because they are no longer working at the company.
The real issue is whether the vesting structure still reflects the timeline of the company.
Four years may make perfect sense for employees in many situations, but startups themselves often take much longer to mature. A company might still be years away from a Series B, Series C or an exit when the founder vesting period has already ended. This is why founders should at least consider whether five or six years might be more appropriate, whether vesting should be weighted more heavily toward later years, or whether additional mechanisms should apply when a founder leaves.
Another important distinction is the difference between economics and control. A former founder can have a legitimate right to keep part of the economic value they helped create without necessarily retaining the same ability to influence operational decisions, financing rounds or future governance. Those are separate questions and should be treated as such.
The difficult part is that most of these problems cannot be fixed elegantly after the fact. Once shares have vested and there are no contractual mechanisms in place, asking someone to simply hand back 10% of the company is unlikely to be a realistic solution. By that stage, the discussion is usually no longer theoretical either. Relationships may already be strained, and what started as a cap table problem can quickly turn into a founder conflict.
That is why the best time to discuss founder departures is when everyone is still getting along.
Founders should not only agree on how equity is divided today. They should also decide what happens if one person leaves after two, three or five years, whether there are buyback rights, how voting and governance rights change, and what a fair outcome should look like for both the departing founder and the company.
Four-year vesting with a one-year cliff is a useful default. It is not a law of nature.
The better question is not: How do we prevent a departing founder from keeping too much equity?
It is: How do we design ownership so that past contribution is rewarded without creating problems for the company’s future?
And that question is much easier to answer on day one than in the middle of a founder breakup.


Hinterlasse einen Kommentar